Category: Federal Agencies & Oversight

  • Trump Signs Pro-Rancher Executive Orders. The Timing Is the Story.

    On September 4, 2026, President Trump signed two executive orders and the USDA announced six additional administrative actions under its Ranchers First Initiative — all framed as the culmination of a historic commitment to America’s cattle producers. The substance of many of these actions is real. The timing, however, is harder to square with the headline.

    One day earlier, a 90-day window opened in which the administration’s plan to import up to 300,000 metric tons of foreign beef would begin taking effect. That plan, which sent cattle futures lower and drew swift backlash from ranchers, Republican lawmakers, and agricultural groups, is conspicuously absent from the USDA press release announcing yesterday’s actions.

    The Herd Problem Is Real

    The policy context the administration cites is accurate. The U.S. cattle herd stood at 86.2 million head as of January 1, 2026 — the smallest inventory recorded since 1951, according to USDA’s National Agricultural Statistics Service. Ground beef averaged $6.89 per pound in July 2026, with beef and veal CPI up roughly 9.4% year-over-year. The squeeze on consumers and the structural challenges facing producers are documented and severe.

    The administration did not create this problem. Herd liquidation driven by drought, high input costs, and decades of market consolidation predates this presidency. The question is not whether the problem is real — it is — but whether the solutions announced September 4 address its root causes, and whether some of them cut against the very producers they claim to protect.

    What Is New, and What Isn’t

    The press release blends genuinely new executive actions with repackaged announcements from prior months. The 2025 USDA Beef Plan, the Ranchers First Initiative, and several programs listed — including the BRAND endorsement for Livestock Risk Protection, the SPUR Guaranteed Loan Program, and the Harvest to Hallways initiative — were announced before September 4. Their inclusion in yesterday’s release as part of a cumulative list of administration accomplishments is standard political communications practice. It is also worth noting when evaluating the scale of any single day’s action.

    The genuinely new items include:

    • Direction to the Secretary of the Interior to begin ESA delisting or downlisting reviews for gray wolves and Mexican wolves
    • Direction to USDA to review authorities for mandatory country of origin labeling (COOL) for beef
    • Direction to prioritize and increase staffing for Packers and Stockyards Act enforcement
    • Expansion of Cooperative Interstate Shipment and Talmadge-Aiken programs for state-inspected meat
    • Enrollment of nearly 1 million new acres in Grasslands Conservation Reserve Program
    • Expansion of USDA’s remote and instrument-enhanced beef grading programs

    The Import Question in the Room

    The executive orders announced September 4 do not mention the administration’s separate August 2026 proclamation to allow expanded beef imports beginning September 1. That action — designed to lower consumer beef prices — drew immediate criticism from ranchers and Republican lawmakers in farm states who argued it would undercut domestic producers already dealing with record-low herd sizes and high operating costs.

    Fox News reported September 3 that Republican lawmakers were warning the White House the import plan was “hurting his base.” Axios characterized the plan as landing “hard in cattle country,” citing falling cattle futures on the announcement. The AP noted ranchers and some Republicans were already balking before the orders were signed.

    The September 4 executive orders — emphasizing predator control, country of origin labeling, and packer competition enforcement — address concerns that domestic ranchers have raised for years. They were signed the day after the import window opened. Whether that sequence reflects careful policy coordination or political damage control is a question the press release does not address.

    Packers and Stockyards: A Long-Deferred Problem

    The executive order directing USDA to prioritize Packers and Stockyards Act enforcement and increase staffing addresses one of the most persistent structural complaints in the cattle industry. Four firms — JBS, Tyson, Cargill, and National Beef — control roughly 85% of U.S. beef processing capacity. That concentration has been documented by USDA’s Economic Research Service, litigated in federal court, and debated in Congress for decades.

    In November 2025, Trump accused foreign-owned meat packers of price manipulation and called for investigation. In April 2025, Senator Grassley introduced bipartisan legislation to strengthen P&S Act enforcement. Yesterday’s executive order does not change the statute — it directs prioritization, increased staffing, and a report to the president within one year. Whether that translates to meaningful enforcement against packers with significant legal and lobbying resources remains to be seen.

    The DOJ Deputy Assistant Attorney General addressed R-CALF USA in 2026 on market concentration in beef processing. The enforcement posture has been announced. The results are pending.

    Country of Origin Labeling: Still Voluntary

    The executive order on country of origin labeling directs USDA to review its authorities for mandatory COOL and produce regulatory and legislative recommendations. It does not impose mandatory labeling. The Product of USA label — which the administration launched as a voluntary standard — remains voluntary.

    Mandatory country of origin labeling for beef was repealed by Congress in 2015 following a WTO ruling that found it discriminated against Canadian and Mexican cattle. Reinstating it would likely require new legislation and could trigger trade disputes. The executive order acknowledges this complexity by directing consultation with the U.S. Trade Representative. That is the appropriate process. It is also a process that could take years and produce no mandatory rule.

    What to Watch

    The actions announced September 4 are not without merit. Expanding small processor capacity, increasing grazing access, modernizing grading technology, and pressing for competitive markets in beef packing are legitimate policy goals with real stakeholder support. The ESA wolf delisting review addresses a genuine and longstanding conflict between ranchers and federal wildlife management.

    But the framing, as in saying the “most pro-rancher administration in history,” invites scrutiny of the full picture, including an import plan that opened the same week, a labeling reform that remains advisory, and a packer enforcement directive that sets a deadline for a report rather than a result.

    The cattle herd is at a 75-year low. Ground beef is nearly seven dollars a pound. The administration’s diagnosis is correct. Whether September 4’s prescriptions match the severity of that diagnosis, or whether they are calibrated more precisely to the political moment, is the question ranchers, and voters in farm states, will be watching.


    Sources: USDA NASS Cattle Inventory Report (Jan. 30, 2026); USDA ERS Livestock, Dairy and Poultry Outlook (May–June 2026); BLS Consumer Price Index (July 2026); White House Fact Sheet (Aug. 2026); AP (Aug. 21, 2026); Axios (Sept. 3, 2026); Fox News (Sept. 3, 2026); Roll Call (Aug. 21, 2026); DOJ Remarks at R-CALF USA 2026; USDA Packers and Stockyards Division enforcement records.

    Fediverse Reactions
  • The Leviathan’s Paperwork Problem: How the VA Quietly Shortchanged Veterans and Called It Due Process

    Closed Means Nothing If the Work Was Never Done

    Here is the sentence that should be carved above the entrance to every regional VA office in America: the claim status “closed” is defined as “the claim is complete with no further action possible.” That is the government’s own definition, straight from VBA Manual 21-4.

    Now consider that the Office of Inspector General just spent thirteen months proving that VBA staff closed thousands of these supposedly complete, no-further-action-possible claims while the actual required action, the one affecting a veteran’s monthly paycheck, had never happened at all.

    Somewhere a bureaucrat defined “closed” and somewhere else an entirely different bureaucrat closed a case that was, by any honest reading, wide open. This is the kind of contradiction that would get you fired from a lemonade stand. At the VA, it just gets you a “concur” stamp and a target completion date sometime next year.

    A Third of Cases, A Thousand Ways to Fail a Veteran

    The report in question, released last week and quietly filed under a review number nobody will remember, examines how the Veterans Benefits Administration handles “adverse actions,” the bureaucratic euphemism for cutting a disabled veteran’s monthly check. Under 38 C.F.R. Section 3.103, before VA can reduce or terminate a veteran’s disability compensation, it has to notify them, give them sixty five days to respond with evidence, and offer a hearing.

    This is not some newfangled progressive innovation. It is basic due process, the kind of thing that has been settled law in this country since well before most of the claims processors involved were born.

    The OIG sampled 229 cases out of an estimated pool of 27,100 and found errors in roughly a third of them, projecting that about 9,300 cases involved at least one mistake (see the report’s Appendix C for the full statistical gymnastics, margin of error and all). Break down the error types and you get a portrait of an agency that treats due process as optional homework.

    About 4,000 cases involved insufficient notice to the veteran, meaning VA moved to cut a check before telling the person whose money it was. Nearly 2,900 involved uncorrected “codesheets,” the internal ledgers that track a veteran’s disability history, left inaccurate after the fact. Another 2,900 had botched effective dates, sometimes off by a month in either direction (see Example 2 in the report, where a claims processor miscounted sixty days and cost a veteran an extra month of benefits they were never entitled to, an overpayment of roughly $300 that will eventually have to be clawed back from someone who did nothing wrong).

    Then there is Example 3, which deserves its own museum exhibit. A veteran’s lung cancer rating was proposed for reduction from 100 percent to 30 percent. The due process letter went out. The veteran did not respond. So far, bureaucratically unremarkable. Then a different claims processor, working an entirely separate benefit for the same veteran, canceled the “end product” tracking the reduction, which under VA’s own system definitions automatically closed the case as complete.

    The reduction that was supposed to happen never did. VA overpaid the veteran about $43,000 over sixteen months, at a running rate of $2,700 a month, and nobody noticed until the OIG went looking. This is not fraud. Nobody here is a villain twirling a mustache. It is simply a records system so brittle that one employee’s unrelated paperwork can silently erase another employee’s entire adjudication, and an agency with no automated way to notice when that happens.

    If this sounds familiar, it should. Federal courts have spent decades wrestling with agencies that treat procedural notice requirements as a formality to be checked off rather than a substantive right to be honored. The Supreme Court’s own due process jurisprudence in the benefits context traces back to Mathews v. Eldridge, which set the very balancing test the VA is nominally supposed to be applying here. And this is far from the VA’s first rodeo with the OIG on exactly this theme.

    Earlier reviews have flagged similar breakdowns in how VBA tracks pending claims through its “end product” workload system, a structure originally built to measure employee productivity rather than to safeguard veterans’ rights, which may explain why it is so good at counting closed cases and so bad at noticing which ones should not have been closed.

    They Knew in 2024. They Made a Video.

    What makes this report more than a dry compliance exercise is the timeline buried in its own pages. In March 2024, over two years before this report’s publication, a senior quality reviewer at VBA’s Compensation Service flagged on an internal call that an “alarming number” of adverse action claims were being closed without final decisions. The recommended fix was to remind new staff to finish their paperwork.

    Nobody followed up.

    The OIG then found the exact same problem persisting through September 2025, in nine of twenty sampled cases, a 45 percent failure rate that is arguably worse than the original estimate. This is bureaucracy’s favorite trick: identify the problem, hold a call about the problem, and mistake the call for the fix.

    Meanwhile, VBA officials proudly told the OIG team about a new training initiative called “Minute Videos,” rolled out in December 2025 with more planned for March 2026. The OIG actually watched them. The December batch had nothing to do with adverse actions. The March batch addressed the topic but, in the OIG’s own words, did not address the deficiencies identified in this review or the actions recommended to mitigate them.

    Somewhere in a windowless conference room, someone approved a training video series that fails to train anyone on the thing it needed to train them on, and that someone almost certainly got a positive performance review for shipping content on schedule.

    VA’s own fix for the letter generating problem, meanwhile, has a “tentative delivery timeline” stretching from a 2023 start date to early 2027, a four year odyssey to standardize a form letter.

    For context, the Government Accountability Office has spent years documenting how federal agencies routinely blow through their own modernization timelines, sometimes by a decade or more, for systems far more complex than a rating decision letter.

    The Bare Minimum, Arriving Four Years Late

    The dollar figures here, at least $16.9 million in improper payments and nearly $1 million a month in ongoing overpayments and underpayments, are almost beside the point, though Congress will fixate on them because dollar figures are legible in a way that human suffering is not.

    The real story is that a veteran who lost a leg or a lung in service to this country can have their monthly check quietly reduced, restored, reduced again, or simply left in bureaucratic limbo because two different employees in two different systems never talked to each other, and no software exists to flag the contradiction.

    VA concurred with every finding. VA agreed to every recommendation. VA has, as of this writing, resolved 184 of the 191 specific errors the OIG identified, which sounds impressive until you remember those 191 are drawn from a sample that represents thousands more the agency has not yet found.

    The recommendations themselves (standardized letters, an extra layer of signoff, an automated tracking report) are not radical. They are the bare minimum any competent organization would have built a decade ago. That the largest disability benefits system in the country is only now getting around to it, under OIG pressure, with completion dates stretching into 2027, tells you less about incompetence than about priorities.

    Building a system that reliably protects a veteran’s paycheck has simply never been urgent enough. It took an audit to make it urgent for exactly as long as this news cycle lasts.

    Fediverse Reactions
  • The BLS Would Like You to Stop Asking Questions About Its Data

    When the Referee Writes His Own Review: BLS, JOLTS, and the Fed

    The Bureau of Labor Statistics just released a paper that can be summarized as follows:

    we investigated our own data and, after a lengthy internal inquiry, have concluded that we are largely correct.

    It is a rare spectacle when a government agency publishes a formal defense brief for itself, complete with charts, footnotes, and the gentle implication that everyone else has been overreacting.

    What JOLTS Actually Counts, Beneath the Hype

    For two years, the Job Openings and Labor Turnover Survey was the celebrity of US labor statistics. JOLTS, as the survey is charmingly named, is a monthly questionnaire sent to about 21,000 nonfarm establishments that asks employers how many jobs they have open, how many people they hired, how many quit, and how many were shown the door. The official FAQ from BLS spells that out in dry, methodical prose, the way only a federal document can.

    During the pandemic recovery, those job openings numbers exploded. From April 2020 through March 2022, the JOLTS series for openings shot upward in a way that thrilled central bankers and terrified anyone who dislikes interest rate hikes. The story was simple: far more vacancies than unemployed workers, which implied a blazing hot labor market that could keep inflation high.

    Then the backlash arrived. Journalists wrote about ghost job postings that never seemed to result in actual hiring, including analysis in the business press that accused fake and duplicate online ads of distorting the picture. Policy researchers and market analysts asked whether the JOLTS openings figures were inflated by overcounting, especially at large firms with many locations and corporate level requisitions. If one requisition is open at 200 stores, is that one opening or 200 openings.

    Into this mini scandal walked three BLS researchers, Larry Akinyooye, Mark Crankshaw, and Sean McIllece, with their paper in the Monthly Labor Review titled, without irony, “Debunking common misconceptions about the Job Openings and Labor Turnover Survey: BLS research disproves overcounting and other myths in JOLTS data.”

    What the BLS Found When It Checked Its Own Homework

    The authors directly confront the overcounting narrative. They argue that the steep climb in openings from 2020 to early 2022 was the result of real economic forces: a surge in labor demand as the economy reopened, fewer available jobseekers, and the rise of remote hiring that broadened recruiting pools. In plain English, employers were genuinely scrambling for workers, and the openings data reflects that scramble rather than some methodological hallucination.

    They then present what amounts to an internal audit. At the micro level, they flag establishment reports that look suspiciously large and examine them in detail. The punchline is a statistic that BLS understandably repeats with some pride: only about 0.27 percent of reports were identified as potential overcounts, and those reports accounted for roughly 0.31 percent of weighted employment in the sample. Their conclusion is that even if every single one of those were wrong, the effect on national openings estimates would be minimal.

    At the macro level, they compare trends in openings reported by single unit establishments to those reported by multi unit firms. If inflated corporate requisitions were massively skewing the data, you would expect multi unit employers to show very different patterns. Instead, the two groups track each other closely, which the authors present as further evidence against a systemic overcounting problem.

    They also remind readers of a detail that got lost in the ghost jobs fever: JOLTS does not scrape data from online job boards. It collects information directly from surveyed employers. Whatever problems exist in online listings, they are not mechanically imported into the published JOLTS statistics.

    So far, so reassuring. Then, in a section not blessed with a headline, the authors acknowledge that JOLTS response rates have been falling and that this is a concern that deserves further research. In a paper devoted to proving that everything is mostly fine, this is the line that should linger.

    When JOLTS Met the Federal Reserve

    The BLS paper would be an internal cleanup operation if JOLTS had remained a niche series for labor economists and trivia buffs. It did not. The Federal Reserve elevated job openings to starring status in its story about inflation and “labor market tightness.” The June 2023 Monetary Policy Report, for example, points explicitly to JOLTS openings as evidence that the labor market remained very tight relative to available workers.

    That tightness narrative helped justify higher interest rates and a willingness to keep them elevated while inflation cooled. In that framework, high vacancy rates implied firms were still bidding aggressively for scarce workers, which in turn threatened to keep wage growth and prices uncomfortably high.

    Not everyone bought the vacancy story. Economists at the Federal Reserve Bank of Minneapolis took a hard look at vacancy measures and hiring outcomes and found something more sobering: fewer openings, and a hiring process that seemed harder for workers, led them to conclude that the US labor market was likely softer than headline indicators suggested. In other words, if you relied on the shiny openings numbers alone, you risked overestimating how much heat was left in the labor market.

    Outside the Federal Reserve System, Congress and oversight agencies circled the same issue from different angles. The Congressional Research Service produced explainers walking through what JOLTS does and does not measure and why lawmakers suddenly cared about a survey that had been running quietly since 2000. The broader debate also drew on Indeed and other online job-posting data as economists explored whether private vacancy measures could supplement or cross-check the official survey. That question entered the congressional record when Reuters reporting on the divergence between JOLTS and private measures was submitted for inclusion in a House Agriculture Committee hearing by Committee Chairman Rep. Glenn Thompson of Pennsylvania.

    The Government Accountability Office, asked to take a broader look at federal economic statistics, concluded that core measures generally meet user needs but also highlighted opportunities to improve data quality and coordination. Translation: reliable enough to steer policy, but do not confuse the dashboard with reality.

    Ghosts, Divergences, and the Comfort of Clean Narratives

    The public fixation on ghost jobs speaks to a broader discomfort. When Forbes publishes pieces arguing that fake or stale postings might distort perceptions of demand, it is channeling the suspicion that the labor market story was too neat. A flood of online listings, corporate performative hiring, and pro forma posts created the impression of abundance even as job seekers told very different stories.

    Experimental indicators have not always backed up the official narrative either. The Conference Board, for instance, has maintained experimental vacancy nowcasts that at times diverge from JOLTS readings. That does not prove JOLTS is wrong, but it does remind us that different measurement tools can paint different pictures of the same labor market.

    Even within the federal data machine, the message is more nuanced than the BLS headline suggests. The GAO calls for quality improvements. Regional Fed researchers warn that vacancy data may exaggerate tightness. CRS patiently reminds lawmakers that every economic indicator has limits. Then BLS publishes a paper that tells the world: relax, the overcount is about a quarter of a percent and hardly moves the needle.

    Who Watches the Watchers of the Labor Market

    The 0.27 percent figure is not trivial. It is genuinely useful to know that a microscopic slice of employer reports appears to drive very little of the national openings total. If the critique was that JOLTS was riddled with phantom vacancies invented by clerical error, the BLS researchers have assembled a solid rebuttal.

    But the most consequential sentence in their paper is the one about declining response rates and the need for more research. That issue goes straight to the heart of statistical legitimacy. If fewer employers answer the phone or the email, and if the ones who do differ in meaningful ways from those who ignore the survey, then the problem is not inflated corporate counts. It is that the sample may drift away from the real economy while everyone keeps treating the top line numbers as gospel.

    Meanwhile, the Federal Reserve has already used JOLTS openings as a key input in deciding how hard to lean on the economy. Congress has already held hearings that treat these statistics as largely authoritative. Job seekers have already lived through a cycle where advertised abundance coexisted with stubbornly difficult searches.

    So yes, it matters that BLS finds only a 0.27 percent overcount. It also matters that, beneath the triumphant title, the same agency quietly flags a basic vulnerability in the survey on which a great deal of policy now rests. The data guardians have graded their own exam and awarded a reassuring score, while noting in the margin that the testing room is getting emptier.

    The open question is not whether JOLTS is fraudulent. The open question is who, exactly, will keep interrogating the numbers the next time a single jobs series becomes the hinge for trillions of dollars in economic decisions. When the referee writes his own review, the least the rest of us can do is read the footnotes.


    Fediverse Reactions
  • Meet the Fourth Branch: Why Your Government Moonlights as a Business (and Mostly Loses)

    A Business That Wasn’t Allowed to Act Like One

    Somewhere in a filing cabinet in 1945, Congress wrote a law with a genuinely funny premise: certain federal agencies would no longer behave like federal agencies. They would sign contracts, hold property, and pay their own bills, just like a business, because Congress had decided the government needed businesses it could own outright without admitting that’s what it was doing.

    Eighty years later, the flagship product of that experiment, the United States Postal Service, has lost money in nearly every fiscal year since 2007, and its cumulative net losses over that period have run to roughly $118 billion, according to GAO’s most recent Postal Service Primer. USPS has been sitting on the Government Accountability Office’s High Risk List, the federal government’s own list of things it privately admits are broken, since 2009. It has been there so long it could apply for tenure.

    This is the joke Congress never quite got around to finishing: build a business that isn’t allowed to act like one, staff it with people who can’t be fired like private employees, price its product below what private carriers charge, and then act baffled, decade after decade, when the balance sheet reads like a hostage note.

    The Law Behind the Contradiction

    The legal machinery behind all this is the Government Corporation Control Act of 1945, now living a quiet life as 31 U.S.C. Chapter 91. It splits federal corporations into two flavors: wholly owned entities like the Tennessee Valley Authority and the Export Import Bank, and mixed ownership entities like the Federal Deposit Insurance Corporation. All of them share one theoretical mandate: generate your own revenue, cover your own costs, and stay off the taxpayer’s tab as much as possible.

    Some of them actually do this. The FDIC funds itself by charging member banks insurance premiums calibrated to risk, which is a business model roughly as old as insurance itself, and it generally runs in the black. TVA sells electricity and, whatever else you think of a federally chartered utility running seven states’ worth of dams, it mostly pays its own way.

    USPS is where the model goes to die, and not for the reasons its critics usually assume. It is not that USPS is bad at commerce. Operating revenue actually rose to $80.5 billion in fiscal year 2025, up 1.2 percent from the prior year, driven partly by its Ground Advantage shipping product actually competing for package business. The problem is that Congress built USPS to run like a business and then, in the same breath, ordered it to behave like a public utility with no off switch. Federal law requires delivery to every address in the country six days a week regardless of profitability, and the Postal Regulatory Commission caps how much USPS can raise prices in response. GAO’s December 2025 report on USPS notes that unfunded liabilities and debt now sit at 206 percent of annual revenue, compared with 82 percent back in 2007. USPS itself has told GAO it could run out of cash as early as fiscal year 2026 if it makes its full required pension payments, a sentence that should alarm anyone who has ever mailed a check.

    Not an Aberration — a Design Feature

    Here is the part that should bother you more than the debt number: USPS is not an aberration inside this system. It is the system working almost exactly as designed, just under conditions the designers never priced in.

    The government corporation model was born out of urgency, not ideology. During World War I, Washington needed to mobilize shipbuilding and war financing faster than a normal federal bureaucracy could move, so Congress chartered entities like the Emergency Fleet Corporation that could hire and contract without civil service delays. The New Deal supercharged the idea. The Reconstruction Finance Corporation alone funneled billions into propping up banks and railroads, operating with a degree of financial autonomy that eventually made Congress nervous enough to write the 1945 Act specifically to rein these entities back in.

    That history matters because it explains why the USSR comparison, while tempting, lands in the wrong place. Soviet state enterprises were just extensions of a central plan, handed production targets by people who didn’t have to care if anyone actually wanted the thing at the other end. American government corporations are weirder. On paper, they’re told to hustle for their own money and act like everyone else in the marketplace. In practice, they live and die on what Congress lets them do, what Congress lets them borrow, and how generous Congress feels after the crash. This is not five-year-plan territory. It’s stranger than that: a business shoved into a market and then told, in the fine print, that it isn’t allowed to make the choices an ordinary business would have to make to stay alive there.

    You can watch the same tension in the 2008 conservatorship of Fannie Mae and Freddie Mac, technically government sponsored enterprises rather than government corporations, but built on the identical fantasy that a market-facing entity can carry an implicit public backstop without anyone ever having to write a check for it, until suddenly someone does.

    The Asterisk in the Promise

    The quiet danger in all of this is not that the government owns pieces of the economy. Plenty of stable democracies run public rail, postal, or utility operators without collapsing into command economies. The danger is the specific American habit of pretending these entities are self-sufficient businesses right up until the moment the bill comes due, at which point Congress rediscovers that USPS’s unfunded liabilities are, in fact, everyone’s problem.

    That accounting fiction has a cost, and it is not abstract. USPS retirees depend on pension funds whose solvency is now genuinely in question. Rural communities depend on a delivery mandate that the agency’s own revenue cannot support at current rates. And taxpayers who were told for eighty years that these corporations don’t touch their money are one legislative rescue away from finding out that promise had an asterisk the whole time.

    This series is going to keep pulling that thread. Next up: the Reconstruction Finance Corporation, the New Deal’s favorite off-balance-sheet slush fund, and what it can teach us about every government bailout that came after it.

  • Truth Social Banned a Federal Accountability Outlet. It Won’t Say Why.

    Editor’s note: This article reports on an action taken against Bureaucracy Times’ own Truth Social account. It is written in the third person for consistency with our editorial style. The appeal referenced below was submitted by the editor on September 4, 2026.

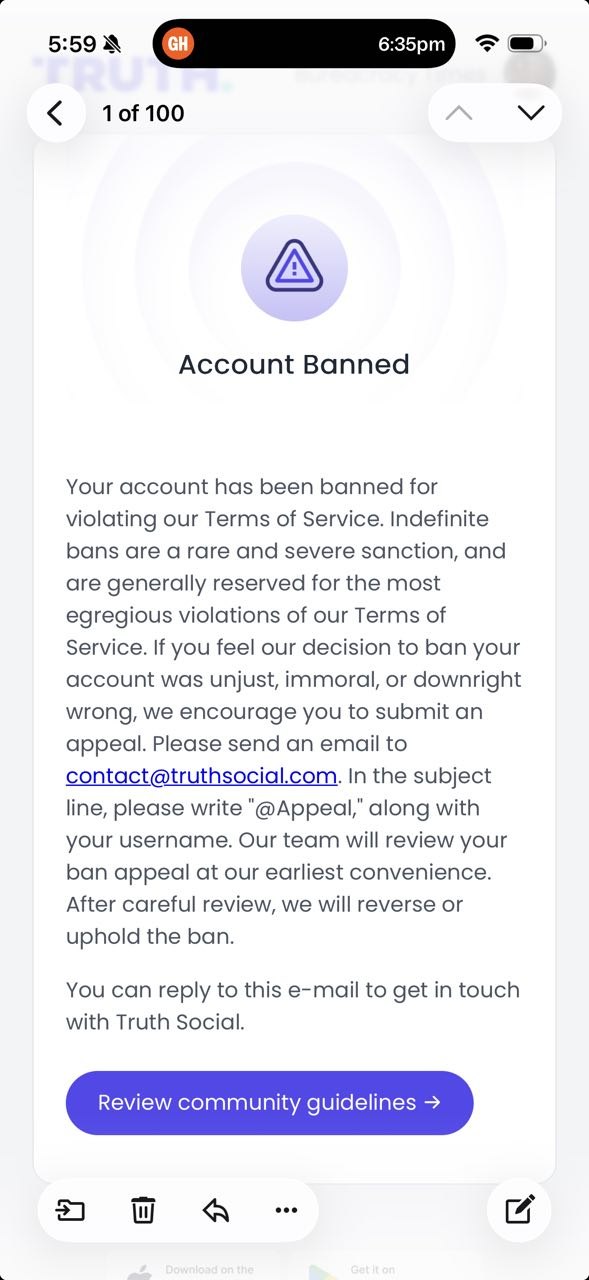
    Bureaucracy Times was banned from Truth Social on September 4, 2026. The notification cited a violation of the platform’s Terms of Service. No specific rule was identified. No content was flagged. No warning was issued.

    Bureaucracy Times covers federal agency accountability, government oversight, regulatory failures, and congressional conduct. The ban is indefinite.

    Truth Social account banned notification
    The notification Bureaucracy Times received from Truth Social on September 4, 2026.
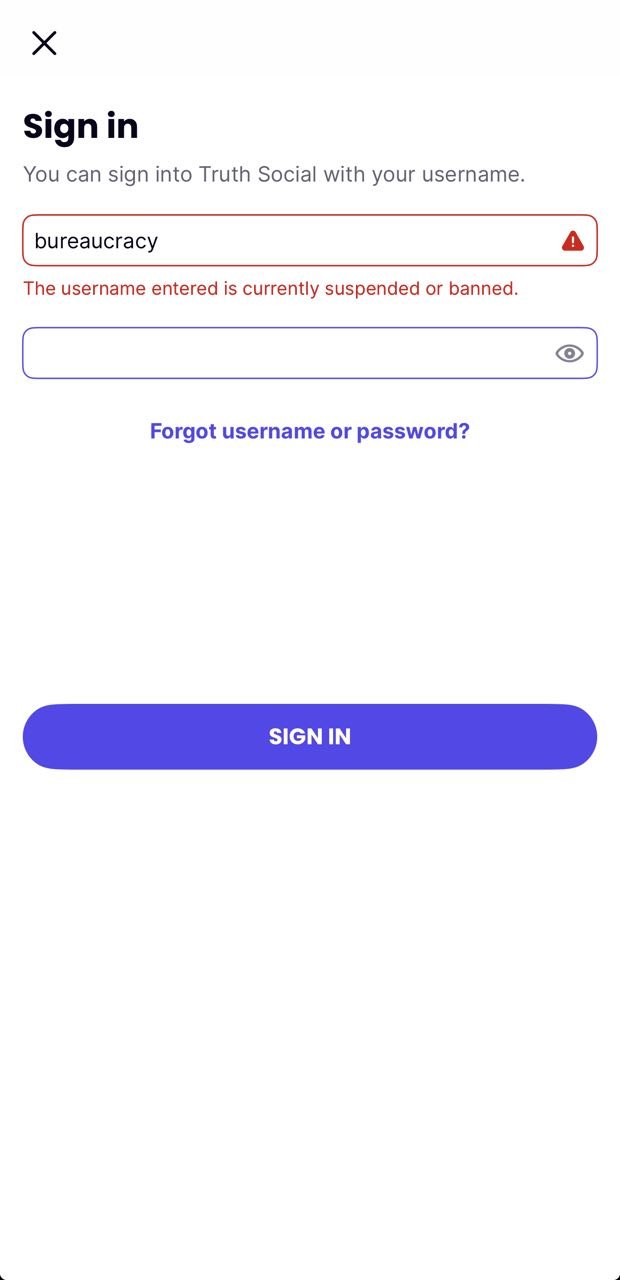
    Truth Social app login screen showing account banned or suspended error
    Attempting to log in to the Truth Social app on September 4, 2026, after receiving the ban notification. The app displays a red error on the username field, offering no further explanation.

    What the Notification Said

    The ban message stated that the account had been banned indefinitely for “violating Terms of Service” and that the violation was “generally reserved for the most egregious violations.” It directed the account to contact@truthsocial.com with a subject line of “@Appeal” followed by the account username.

    The account handle — @bureaucracy — is a common English word. Whether the simplicity or genericness of the handle factored into any complaint or automated flag is unknown. Truth Social’s guidelines identify “username squatting” as a reportable offense, but that category applies to accounts impersonating others, not to a publication operating under its own editorial identity.

    That is the entirety of the explanation provided.

    What the Guidelines Actually Say

    Truth Social’s Community Guidelines open with a commitment to free speech principles:

    “In no instance will TRUTH Social determine what content will be removed or filtered, or whose account will be eliminated, on the basis of the point of view shared within the content at issue. TRUTH Social’s policies are, to use a popular concept in First Amendment law, viewpoint-neutral and fully inclusive.”

    The guidelines list eleven categories of reportable content — illegal activity, fraud, nudity, violence, child sexual abuse material, prostitution, counterfeit goods, privacy violations, illegal sales, intellectual property infringement, and doxxing — and four categories of reportable account behavior: spam/bots, username squatting, impersonation, and intellectual property violations.

    Bureaucracy Times publishes investigative reporting on federal agencies, regulatory failures, congressional oversight, and government accountability. Its content is sourced from public records, GAO reports, Inspector General findings, FOIA requests, and official government documents.

    None of the fifteen enumerated violation categories apply.

    The Accountability Gap

    Truth Social was founded by President Donald Trump following his suspension from Twitter in January 2021. The platform has consistently marketed itself as a free speech alternative to what it characterizes as ideologically biased Big Tech moderation.

    The guidelines promise viewpoint neutrality. The enforcement is a black box.

    There is no published appeals process beyond a single email address. There is no timeline for response. There is no mechanism to identify which content triggered the ban, which rule was applied, or who made the decision. The notification itself acknowledges none of this. It simply states a violation occurred and offers an email address.

    This is the same accountability gap Bureaucracy Times covers when federal agencies deny FOIA requests without explanation, when regulatory bodies issue enforcement actions without citing specific violations, or when government offices respond to oversight inquiries with form letters and indefinite timelines.

    The irony is structural, not incidental.

    What Happens Next

    Bureaucracy Times submitted an appeal to Truth Social on September 4, 2026, via email to contact@truthsocial.com with the subject line required by the platform. We will report on any response received, including the timeline, the substance of any explanation, and whether the ban is reversed.

    We are also documenting this incident as a case study in platform moderation opacity, the same kind of opacity we cover in the institutions this publication was built to hold accountable.

    If Truth Social responds, we will update this article. If it does not, that will be the story.

    Update, September 7, 2026: Truth Social responded to the appeal and reinstated the @bureaucracy account, stating, “Your account was inadvertently banned due to a bug in our bot mitigation system that mistakenly identified your account as a bot. We apologize for the error and have fully reinstated your account.”

    This explanation identifies a technical mechanism for the ban but does not clarify why a government accountability outlet was flagged as a bot, nor why the original notification cited a Terms of Service violation rather than a technical error.

  • We Asked the SEC to Explain the MMTLP Halt. They Said Wait — and Denied Our Expedited Request.

    Bureaucracy Times filed a Freedom of Information Act (FOIA) request seeking SEC records on FINRA’s unexplained December 2022 MMTLP trading halt. The SEC acknowledged the request within 24 hours, and promptly denied expedited processing the same day.


    On September 1, 2026, Bureaucracy Times submitted a formal Freedom of Information Act request to the U.S. Securities and Exchange Commission. The request sought records related to FINRA’s December 9, 2022 trading halt on MMTLP, a halt that locked approximately 65,000 retail investors into a private company with no public market and for which no specific triggering event has ever been publicly identified.

    The SEC acknowledged the request on September 2. By September 3, an SEC attorney advisor had issued an adverse determination: expedited processing denied.

    Seventy-two hours. Request. Acknowledge. Deny.

    What We Asked For

    The FOIA request (assigned tracking number 26-02765-FOIA) covers a six-category scope of records for the period June 1, 2022 through the date the request is processed:

    1. SEC-FINRA communications regarding the MMTLP halt, including emails, letters, memoranda, meeting notes, instant messages, and internal reports relating to the U3 Extraordinary Event Halt imposed under FINRA Rule 6440.
    2. SEC review records reflecting whether the Commission concurred in, was notified of, questioned, or evaluated FINRA’s halt authority before or after it was exercised.
    3. Records identifying the “extraordinary event” cited in FINRA’s Uniform Practice Advisory #35-22 (December 9, 2022) as the basis for the halt — a triggering circumstance FINRA has never publicly named.
    4. Records related to the threshold list error. FINRA’s acknowledgment that MMTLP was erroneously listed on the OTC Threshold Securities List for approximately 41 days due to a systems coding error, and any SEC review of potential Regulation SHO or FINRA Rule 4320 obligations that error may have triggered.
    5. Congressional correspondence communications between the SEC and FINRA, or between the SEC and any member of Congress or congressional staff, regarding the MMTLP halt and the subsequent distribution of Next Bridge Hydrocarbons common stock to former MMTLP shareholders.
    6. SEC oversight of FINRA’s public communications including FINRA’s FAQ and Supplemental FAQ on the MMTLP halt, to the extent the SEC reviewed, commented on, or was consulted in connection with those publications.

    The full FOIA request is embedded below.

    The SEC’s Response: Acknowledged, and Queued

    The SEC’s Office of FOIA Services acknowledged the request on September 2, 2026. The acknowledgement confirmed the tracking number and disclosed three reasons the agency would not meet FOIA’s standard 20-day statutory response window, which would invoke the permitted 10-day extension:

    • The need to collect records from an organization geographically separated from the FOIA office
    • The potential volume of responsive records
    • The need for consultation with other SEC offices with a substantial interest in the subject matter

    In plain terms: this request is complicated, there may be a lot of records, and multiple parts of the SEC need to weigh in. The agency placed the request in its standard processing queue.

    Requesters who do not receive a response within 30 business days may seek dispute resolution through an SEC FOIA Public Liaison or the Office of Government Information Services (OGIS).

    The Denial: No “Compelling Need” Demonstrated

    Also on September 3, Attorney Advisor Matthew Hurd issued the SEC’s interim response, a formal adverse determination on the expedited processing request.

    Under the SEC’s FOIA regulation, 17 C.F.R. § 200.80(d)(7), expedited processing is available when a requester demonstrates a “compelling need” as defined in one of two ways:

    • A failure to obtain the records on an expedited basis could reasonably be expected to pose an imminent threat to an individual’s life or physical safety, or
    • The requester is primarily engaged in disseminating information, and there is an urgency to inform the public of actual or alleged Federal government activity

    Bureaucracy Times requested expedited processing under the second prong, as a news publication covering federal regulatory accountability, with an active public interest in the unresolved basis for a regulatory action that permanently affected tens of thousands of investors.

    The request cited active congressional inquiry, ongoing litigation, and the absence of any public explanation for the triggering “extraordinary event.”

    Hurd’s determination was brief and unequivocal: “In my view, a compelling need has not been demonstrated. Therefore, we are processing your request under our normal guidelines.”

    No further explanation was provided. The SEC offered no analysis of the urgency standard as applied to the facts of the request; no finding that the subject matter lacked public significance, no ruling that the congressional and litigation context was insufficient, and no guidance on what a successful expedited request would have looked like.

    Just: no.

    One Thing the SEC Did Grant

    The adverse determination was not a total loss. The SEC placed Bureaucracy Times in the “media use” fee category, confirming that search and review services are provided at no charge. As the SEC’s letter notes, records are typically released electronically and copy costs are not assessed, rendering the fee waiver request moot.

    It’s a small acknowledgment, but a meaningful one: the SEC’s own FOIA office confirmed that this is legitimate journalism on a matter of public concern.

    What Comes Next

    Bureaucracy Times has 90 calendar days from September 3, 2026 to appeal the expedited processing denial to the SEC’s General Counsel under 5 U.S.C. § 552(a)(6) and 17 C.F.R. § 200.80(f)(1). We are evaluating that option.

    On the underlying records request, the SEC disclosed in the same letter that it is “consulting with other SEC staff” regarding the request, and that it will notify us of its findings upon completion. That consultation, combined with the three-part rationale for the extended processing timeline, suggests that responsive records, if they exist, are not sitting in a single office. They span organizational boundaries.

    Which is exactly what you’d expect for a regulatory action that no single office has ever publicly explained.

    We will report what we receive and what we don’t.


    This article is Part 2 of Bureaucracy Times’ ongoing coverage of the MMTLP trading halt. Part 1 examines the halt itself and the questions that remain unanswered three years later.

    Questions about this FOIA request or the MMTLP coverage? Contact robert@hannotek.com.

    Fediverse Reactions
  • The Halt That Has No Answer: MMTLP, FINRA’s Unexplained “Extraordinary Event,” and 65,000 Investors Still Waiting

    The Extraordinary Event That Never Got Explained

    On the morning of December 9, 2022, trading in one of the more obscure corners of the U.S. equity markets stopped and never resumed. FINRA, the private self-regulatory body that oversees broker-dealers and many over-the-counter securities, issued a U3 halt on MMTLP, the OTC ticker for Meta Materials Inc.’s Series A Preferred Stock. The code signaled an “extraordinary event.” In practical terms, it meant the stock was frozen. There would be no reopening auction, no final day of speculative mania, and, crucially for thousands of retail investors, no last chance to exit.

    U3 halts are rare in the over-the-counter market, reserved for situations in which regulators believe continued trading could produce disorderly conditions or serious settlement failures. When the halt hit, investors expected two more trading days before their preferred shares were canceled as part of a planned corporate action. Instead, they watched their screens go dark, then learned that the symbol would never reappear. The security was effectively terminated in mid-sentence.

    More than three years later, there is still no public, granular explanation of what the “extraordinary event” actually was. What exists instead is a patchwork: a self-regulator asserting broad authority with minimal disclosure, an ongoing but unresolved SEC investigation, a set of serious but contested investor allegations, and tens of thousands of shareholders holding illiquid interests in a private company with no public market. The case has become a stress test for how much opacity the American regulatory architecture will tolerate when retail investors are the ones left holding the bag.

    From Torchlight to MMTLP to Next Bridge

    To understand why this halt matters, it helps to follow the corporate trail. MMTLP was not a traditional operating company. It was the OTC symbol assigned to Meta Materials’ Series A Preferred Stock, a spin-off vehicle born when Torchlight Energy Resources, an oil and gas company, merged with Meta Materials, a Canadian tech firm, in 2021. Torchlight investors received preferred shares representing an interest in Torchlight’s legacy oil and gas assets, which were to be separated into a new entity.

    That new entity eventually became Next Bridge Hydrocarbons, Inc. By late 2022, the path appeared straightforward on paper. MMTLP shares would be canceled on December 14, 2022, and holders of record would receive one share of Next Bridge common stock for every MMTLP share they held. The preferred shares functioned as a bridge from the old Torchlight assets into the new private company.

    In practice, MMTLP had turned into something else entirely. As the distribution date approached, the preferred shares evolved into a speculative meme-like OTC play. Social media channels amplified bullish narratives. Retail trading surged. Short sellers saw an opportunity on the other side. By late 2022, MMTLP was heavily traded and heavily shorted, according to public data on short interest and fails-to-deliver. The convergence of a complex corporate action and a highly volatile retail-driven market is precisely the sort of scenario that tests the limits of regulatory systems.

    A Halt with Powerful Discretion and Limited Disclosure

    FINRA’s stated authority for the halt sits in Rule 6440, which allows the organization to suspend trading in OTC equity securities under a range of circumstances, including when an extraordinary event has had or may have a material effect on the market or could cause major disruption or uncertainty in the settlement process. The rule gives FINRA wide discretion. It does not require the organization to publicly identify the specific triggering event, nor to publish detailed contemporaneous reasoning.

    On December 9, 2022, FINRA issued Uniform Practice Advisory #35-22, announcing a U3 halt in MMTLP. The notice referenced “extraordinary events” related to the security, but did not describe them. What investors saw was a short advisory, a permanent halt, and a fast-approaching corporate action that would cancel their tradable shares within days. What they did not see, and still have not seen, is a public account of what information or risks justified the nuclear option of freezing trading until cancellation.

    The 41-Day Coding Error and the Enforcement Gap

    In the months that followed, one fact emerged that fueled deeper questions. FINRA acknowledged that a systems coding error had incorrectly classified MMTLP as a non-SEC-reporting security, causing it to be listed on FINRA’s OTC Threshold Securities List for approximately 41 days. The organization disclosed this in a public FAQ, describing it as an error in how the security was coded within its systems.

    The threshold list designation matters because it is supposed to trigger regulatory consequences. Under SEC Regulation SHO and FINRA Rule 4320, securities appearing on the threshold list are subject to “close-out” requirements designed to address persistent failures to deliver shares. If a stock remains on the list, market participants with unsettled short positions are required to buy shares to close those positions within a prescribed time frame.

    Investors and several members of Congress asked a simple but pointed question: if MMTLP was on the threshold list for 41 days, even erroneously, why did that not result in documented enforcement activity or visible forced buy-ins to resolve any outstanding fails-to-deliver? FINRA’s public FAQ acknowledged the incorrect listing and described it as a mistake, but did not provide an answer that critics considered complete on the enforcement issue. The organization has said, in response to congressional inquiries, that its review did not find evidence of significant naked short selling at the end of MMTLP trading, a conclusion that directly challenges one of the central claims of the most vocal investors.

    Shareholders Stranded in a Private Company

    The practical outcome for investors is not disputed. Court filings and company disclosures indicate that roughly 65,000 shareholders held long positions in MMTLP at the time of the halt. On December 14, 2022, the distribution went ahead. Meta Materials distributed 165,472,241 shares of Next Bridge Hydrocarbons common stock to former MMTLP holders on a one-to-one basis.

    Next Bridge is a private company focused on oil and gas assets. As of the company’s May 2026 prospectus filing, its stock is not listed on any public exchange and is not eligible for electronic transfer through the Depository Trust Company. There is no conventional public market where shareholders can simply log into a brokerage account and sell. Instead, they hold paper-like positions in a thin, opaque universe of potential private transfers, company-led liquidity initiatives, or the speculative hope of a future listing.

    For many retail investors who approached MMTLP as a tradable meme stock, the shift from a volatile OTC symbol to an illiquid private equity position was jarring. Whether or not that outcome was avoidable, the process that delivered it — an abrupt permanent halt with limited public explanation — has become the focal point of their anger.

    Allegations, Press Conferences, and an Unanswered Letter

    Out of that anger, a loose movement coalesced under the hashtag #MMTLParmy and later through groups such as American Made Action. Their core allegation is straightforward but unproven: they contend that the U3 halt was effectively orchestrated to shield short sellers and broker-dealers from having to buy back shares ahead of the corporate action, which would have required them to deliver Next Bridge stock they allegedly did not have.

    These investors argue that an enormous level of synthetic or “naked” short interest built up in MMTLP and that the combination of the threshold list anomaly and the abrupt halt prevented a normal reconciliation of supply and demand. They point to anecdotal reports of difficulty obtaining physical share certificates and to the absence of a public, audited share count as circumstantial support. These contentions remain allegations. They have not been validated by regulators or courts, and they are directly contested by FINRA’s own finding that it uncovered no evidence of significant naked short selling in MMTLP at the end of trading.

    The campaign nonetheless gained political traction. On January 12, 2026, investors and advocates held a press conference outside SEC headquarters demanding greater transparency around the halt. Separately, 74 members of Congress, led by Representative Ralph Norman of South Carolina, sent a detailed letter to SEC Chair Gary Gensler and to FINRA. The lawmakers’ questions echoed investor concerns: why did MMTLP sit on the threshold list for 41 days without visible enforcement action, why was no audited share count ever released, and what precisely was the extraordinary event that justified a permanent halt days before a known corporate cutoff?

    FINRA’s Data, the SEC’s Charges, and an Open Investigation

    FINRA responded publicly through an FAQ and, more specifically, in a January 31, 2024 letter responding to Representative Norman. In those materials, FINRA provided additional data on short interest and fails-to-deliver in MMTLP. The organization reiterated that, based on its review, it did not find evidence of significant naked short selling at the end of trading. It also maintained that the halt was necessary to prevent disruption in the settlement of the corporate action that would cancel MMTLP and distribute Next Bridge shares.

    What FINRA has not done is publicly spell out, in granular, chronological terms, what information it received, how it assessed settlement risk, and which specific conditions met the threshold of an “extraordinary event” under Rule 6440. The gap between the broad authority the rule grants and the limited explanation offered is not a matter of market rumor. It is a structural accountability question: how far can a self-regulator go in halting trading permanently while disclosing only the bare minimum required by its own rules?

    Meanwhile, the SEC has drawn a line between the corporate saga that created MMTLP and the unresolved questions surrounding the halt. In June 2024, the Commission filed charges against Meta Materials and its former CEOs, John Brda and Georgios Palikaras, alleging market manipulation and fraud in connection with a $137.5 million at-the-market offering. According to the SEC, that misconduct occurred on the front end of the story — in how Meta Materials raised capital and communicated with the market — not in the halt itself.

    In the same breath, however, the SEC disclosed that a separate investigation into “subsequent events related to Meta Materials” remained ongoing. That phrase is widely understood to include the MMTLP halt and its aftermath. As of the last public update in June 2024, that investigation had not produced any public enforcement action or formal findings about the halt. The existence of an open investigation is not proof that rules were broken. It does, however, mean that the agency is still actively reviewing the very questions investors and lawmakers have been raising.

    A Self-Regulatory Blind Spot

    At the center of the MMTLP controversy is a feature of the U.S. market structure that usually stays offstage. FINRA is not a federal agency. It is a private self-regulatory organization, authorized by Congress and overseen by the SEC, with the power to write and enforce rules for broker-dealers and many OTC securities. Unlike the SEC, FINRA is not subject to the Freedom of Information Act. Its internal emails, memos, and meeting notes about the MMTLP halt are not available via standard public records requests.

    The SEC, for its part, is subject to FOIA but can invoke law enforcement exemptions, including Exemption 7, to withhold records related to ongoing investigations. In the MMTLP case, that means the two entities with the most direct insight into what happened in December 2022 are either not covered by FOIA or have legal grounds to decline disclosure while their inquiries remain open. Congressional oversight can demand answers, but short of a formal hearing or subpoena process, that leverage has so far produced letters and partial responses rather than full transparency.

    The result is a regulatory blind spot that does not require any conspiracy to operate. A self-regulator, acting under a broadly worded rule, can impose a permanent trading halt on a security in the middle of a contentious corporate action. The specific rationale can remain largely undisclosed to the public. The federal overseer can continue to investigate without revealing its working theories or factual findings. Investors, and even lawmakers, can be left to infer intent and causality from fragments of data and carefully worded statements.

    Four Years On, the Question Remains

    As of mid-2026, that blind spot has not closed. The SEC’s investigation related to MMTLP remains open, with no public enforcement action specifically addressing the halt. Next Bridge continues to file with the SEC and has undertaken efforts to respond to shareholder concerns, including a 2026 special dividend of common stock intended, in part, to address perceived allocation and ownership issues.

    Litigation has produced more heat than light. Multiple lawsuits have been filed and largely dismissed, including Targgart v. Next Bridge Hydrocarbons, which was thrown out at the district court level and is now on appeal to the Fifth Circuit. The dismissals have not resolved factual disputes about trading mechanics or regulatory decision-making; they have primarily reflected legal hurdles in holding issuers, regulators, or intermediaries liable under existing statutes.

    Congressional pressure has yielded attention but not yet a comprehensive public accounting. The letter from 74 lawmakers prompted formal replies and some additional data disclosures, but no regulator has published the kind of detailed timeline that would show exactly how and why the U3 decision was made. FINRA stands by its conclusion that it did not detect significant naked short selling at the end of MMTLP trading. Investor groups stand by their allegation that the halt functioned as a bailout for short positions. Between those positions lies a void of shared facts.

    What is clear is that investors who held MMTLP on December 9, 2022 are now involuntary long-term shareholders in a private oil and gas company, waiting either for a path to liquidity or for regulators to explain the decision that cut off their last days of trading. Whether future SEC actions, court rulings, or congressional inquiries will fill in the missing pieces remains uncertain.

    For now, the question at the heart of the MMTLP saga is stark and unresolved: when FINRA called an “extraordinary event” in December 2022, what, exactly, did it see that the public still has not?
    Fediverse Reactions
  • Cox Media Group Was Selling a Lie, and the FTC’s Price Tag Was $930,000

    Active Listening, Passive Accountability: Cox Sold A Phantom Surveillance Machine

    Cox Media Group spent years telling advertisers that its ad tech could listen to people through their phones and smart devices in real time. The Federal Trade Commission just confirmed the truth, and it is not the nightmare people expected. The terrifying surveillance state did not materialize. Instead, one of the largest media companies in the United States apparently charged clients for an eavesdropping machine that did not work as advertised (FTC press release, Aug. 27, 2026). They did not just lie about you. They lied about lying on you.

    The product that promised to hear you breathe

    The centerpiece of this small civic tragedy is a product with the sort of tech conference name that should set off fire alarms: Active Listening. According to pitch materials obtained and published by 404 Media, Cox Media Group, through a web of related entities, told advertisers that Active Listening was an AI powered service that used the microphones on smartphones, smart TVs, and smart speakers to harvest what people said in their homes. The pitch deck promised to “capture real time intent data by listening to our conversations” and to use that data to target ads across digital platforms.

    The deck name dropped Google, Amazon, and Facebook as partners, which instantly raised eyebrows among people who have read an engineering document in their lives. Active Listening, according to the marketing promises, would know when you talked about a new car or a vacation and would help advertisers ambush you with relevant ads on major platforms. Cox sold this as a competitive advantage, the secret sauce that supposedly made its campaigns smarter than the poor souls buying regular ad inventory (404 Media).

    The three company magic trick

    The FTC enforcement action involves three entities: CMG Media Corporation, which does business as Cox Media Group, a major broadcaster and digital publisher. MindSift LLC, described in the complaint as a data and technology firm. And 1010 Digital Works LLC, a company that helped develop and promote Active Listening (FTC complaint). Together they offered advertisers a kind of turnkey wiretap fantasy.

    On paper, CMG handled the sales pitch, MindSift delivered the alleged AI analysis, and 1010 Digital Works supplied the technical wizardry. In reality, according to the FTC, the supposed listening capability was either false or unsubstantiated. The complaint says the companies told customers their service collected and used real time conversational data, when in fact they could not do what they claimed (FTC complaint).

    Security researchers and reporters smelled trouble early. Ars Technica examined the claims in late 2023 and pointed out that no major mobile platform would quietly allow a random ad partner to run a background microphone dragnet across millions of devices (Ars Technica). The word “impossible” was used with unusual restraint. The better word might have been “ridiculous.”

    From leaked slides to federal orders

    The unravelling started when 404 Media published the Active Listening pitch deck, giving the public an unvarnished look at the claims Cox and its partners were making behind closed doors. Gizmodo followed with its own examination of the materials and highlighted just how explicitly the slides promised microphone level access to private conversations for ad targeting (Gizmodo).

    Once those claims hit daylight, the alleged “partners” did not exactly rush to embrace them. Google removed CMG from its Partners Program after the story spread, and Meta reportedly reviewed its relationship with the company (Gizmodo). Senator Marsha Blackburn sent letters in September 2024 to CMG and the platforms that had been invoked in the pitch materials, seeking clarification about what exactly this service did and how (Blackburn letter).

    Under pressure, CMG issued a public statement in September 2024 asserting that Active Listening had been discontinued and insisting that it did not actually listen to private conversations in the way critics feared (CMG response). The company tried to downplay the idea that it was running a live audio surveillance operation, while somehow not conceding that its pitch deck had veered into science fiction.

    The FTC filed its formal complaint on May 21, 2026, and on August 27, 2026, it finalized orders with CMG, MindSift, and 1010 Digital Works, finding that the companies deceived customers about Active Listening’s capabilities (FTC press release). Regulators did not find a vast illegal wiretap plot. They found an ad product that bragged about criminal level access to people’s devices and could not back it up.

    The fine that would not pay for the coffee

    The money involved is almost insultingly small. CMG will pay $880,000. MindSift and 1010 Digital Works will each pay $25,000. The grand total for an AI branded service that allegedly promised live monitoring of household conversations clocks in at $930,000 (FTC press release).

    To grasp the scale, remember that CMG’s parent company, Cox Enterprises, has reported revenue in the tens of billions of dollars in recent years. Against that backdrop, $880,000 looks less like a punishment and more like an invoice for a slightly overpriced consulting engagement. No executive is cancelling a golf trip over this.

    The timeline does not exactly scream urgency. The pitch deck surfaced in late 2023. Google cut CMG loose from its Partners Program soon after. Senator Blackburn raised public questions in September 2024. CMG said the product was discontinued that same month. The FTC did not file its complaint until May 2026, and only finalized the orders in August 2026 (FTC case page). Eighteen months of regulatory process for a fine that amounts to parking ticket money in corporate terms.

    The two sided risk: surveillance or snake oil

    Why does any of this matter, if the microphones were not actually siphoning up your late night rants about car insurance and vacation plans

    Because either version of this story is bad. If Active Listening had worked as advertised, it would look a lot like illegal surveillance. A private media company and its vendors would have been running continuous audio capture through consumer devices in order to sell more ads. The only relief in the FTC’s findings is that this horror show did not come true, at least not here.

    But if the product did not work, then advertisers were paying real money for imaginary data. That is fraud, not merely overenthusiastic marketing. Ad buyers were told they could reach audiences based on intimate, spoken conversations, when in fact the companies could not substantiate that claim. Consumers still lose in this scenario, because a market that rewards outlandish surveillance stories pushes every competitor to gesture at the same dystopian magic, whether they have it or not.

    The FTC’s orders do more than collect a modest check. They impose 20 year prohibitions on future misrepresentations about data collection, surveillance, and AI capabilities for all three companies (FTC press release). The length of that leash says something quiet and grim. Regulators clearly expect that someone will try a version of this trick again.

    For the public, the Cox case settles one narrow question. Your phone was probably not part of a Cox run, AI powered live tap for ad targeting, despite the rumors. What the case does not settle is more troubling. It shows how easily a large, well connected media company can spin a story about total surveillance, use the credibility of big tech brands as set dressing, and sell that fantasy to clients until reporters, platforms, a senator, and finally the FTC call their bluff. The lesson is not that we are safe. The lesson is that when someone tells you they can hear everything you say, the only rational response is to demand proof, and then check who is cashing the checks.


    Fediverse Reactions
  • Space Academy: Blueprint or Budget Trap?

    Federal Register Vol. 91, No. 170 · September 3, 2026 · Pages 56737–56739 · Document 2026-18141


    Agency Identification

    • Issuing Authority: The President of the United States (Executive Office)
    • Administering Agency: National Aeronautics and Space Administration (NASA)
    • Commission Chair: Administrator of NASA
    • Commission Executive Director: A NASA Deputy Administrator designated by the Chair

    Administrative Action

    • Action Type: Presidential Executive Order (No. 14423)
    • Document ID: 2026-18141
    • Filed: September 2, 2026
    • Published: September 3, 2026
    • FR Pages: 56737–56739

    The “Core” Fact

    On August 28, 2026, President Trump signed Executive Order 14423, formally establishing the Presidential Commission on the United States Space Academy. The order directs a NASA-led commission to design a brand-new federal service academy dedicated entirely to space operations, exploration, and leadership.

    The Commission has 120 days from the date of the order to deliver a report to the President covering six specific mandates:

    1. Governance Framework — including explicit evaluation of placing the Academy within NASA
    2. Academic and Leadership Curriculum — degree programs, technical training, and leadership development pipeline
    3. Service Obligations — what graduates owe the government in exchange for a federally funded education
    4. Applicant Prerequisites — eligibility standards for admission
    5. Location Selection Process — a framework for choosing where the Academy will be built
    6. Administrative and Legislative Actions — what Congress will need to authorize and what agencies must do to implement the plan

    In short: the EO doesn’t build an academy. It builds a committee to design one.


    What the Order Actually Does (and Doesn’t Do)

    Section 4 of EO 14423 contains the standard boilerplate that every skeptic of executive orders should read first: the order “shall be implemented consistent with applicable law and subject to the availability of appropriations.”

    Translation: Congress has to pay for it.

    No funding is appropriated by the order itself. No land is acquired. No curriculum is written. No class of cadets is enrolled. What exists today — the day it was published in the Federal Register — is a commission with a 120-day clock and a NASA administrator holding the gavel.

    That’s not nothing. The existing service academies (West Point, Annapolis, Colorado Springs) each cost the federal government roughly $200,000–$400,000 per graduate to operate annually. A space-focused academy built from scratch, with specialized facilities, simulation technology, and a curriculum straddling aerospace engineering, military doctrine, and orbital mechanics, will not be cheap. Independent estimates for a comparable institution run well north of $1 billion in startup costs before the first class ever reports for duty.

    The Commission’s report — due by late December 2026 — will be the real document to watch.


    The NASA Question

    The most substantive policy choice buried in Section 3 is the explicit instruction that the Commission must evaluate placing the Academy within NASA…not the Department of Defense, not the Space Force, not a standalone entity.

    This is a notable departure from the obvious gravitational pull of the U.S. Space Force, which already trains space operators and has its own officer pipeline. Critics will note the tension immediately: the Space Force exists to militarize space operations, while NASA’s statutory mission is civilian exploration and scientific research under 51 U.S.C. § 20102.

    Grafting a service academy, with its service obligations, military-style governance, and federal commissioning structure, onto a civilian science agency is not a minor administrative tweak. It would require significant Congressional action to grant NASA the statutory authority to run what is effectively a military-adjacent institution.

    Whether the Commission recommends NASA as the host, defers to DoD, or proposes a hybrid model will define the legislative battle that follows.


    Taxpayer & Public Impact

    • Projected Cost/Budget: TBD. The cost is contingent on the Commission’s report and subsequent Congressional appropriation. Comparable greenfield service academy construction has historically exceeded $1 billion.
    • Commission Report Deadline: Approximately late December 2026 (120 days from August 28, 2026)
    • Location: To be determined by Commission recommendation
    • Congressional Action Required: Yes. Authorization and appropriations legislation will be necessary before any Academy can be established

    Bottom Line Up Front

    Executive Order 14423 is a visionary statement wrapped in a procedural shell. The concept of a United States Space Academy, like a West Point for the final frontier, is the kind of bold institutional declaration that generates headlines and congressional interest in roughly equal measure.

    The hard truth is that EOs of this type live or die in the 120 days that follow. If the Commission delivers a credible, costed, legislatively actionable plan by December, Congress may take it seriously. If it produces a vague framework with institutional turf fights baked in, particularly the NASA-vs.-Space Force question, this joins a long list of commissions whose reports are filed and forgotten.

    The space domain is real. The talent pipeline gap is real. Whether a new federal academy is the right solution, versus expanding existing Space Force training pipelines or partnering with established universities, is a question the Commission is supposed to answer.

    Watch the December report. That’s when the blueprint either becomes a building or becomes a budget trap.


    “The Space Academy commission faces the same institutional question that haunts other Pentagon-adjacent initiatives: whether the public accountability machinery can keep pace with what’s happening inside. Our coverage of CYBERCOM’s information blackout — a command that announced its largest-ever reorganization without a single press release on its own website — is a preview of what happens when institutions treat transparency as optional.”

    https://www.federalregister.gov/documents/2026/09/03/2026-18141/establishing-the-united-states-space-academy


    Investigative Tags: #ExecutiveOrder #SpaceAcademy #NASA #SpaceForce #PresidentialCommission #FederalRegister


  • Paper Workflows and Empty Corridors: The VA’s Mountain Home Problem

    Mountain Home Has Been Here Since 1903. It Still Needs Written Instructions To Call You Back.

    VA Mountain Home Healthcare System sits on a historic campus that opened around 1903 as the Mountain Branch of the National Home for Disabled Volunteer Soldiers. A century and change later, the institution that learned how to treat trench lung and mustard gas injuries just received a formal reminder from its own watchdog that staff should have written instructions for telling patients their test results. Not how to interpret the results. Not how to treat the disease. How to pick up the phone.

    On August 28, 2026, the VA Office of Inspector General released an inspection of the VA Mountain Home Healthcare System in Johnson City, Tennessee, also known as the James H. Quillen VA Medical Center. The system serves veterans across a 32 county patch of northeastern Tennessee, southwestern Virginia, and southeastern Kentucky. After examining quality, leadership, and patient care, the OIG landed on a single recommendation: the facility must create written, service level workflows for communicating test results, consistent with Veterans Health Administration Directive 1088(1), Communicating Test Results to Providers and Patients.

    In plainer English, the oldest veteran campus in the system needed Washington to tell it to write down who calls whom, when, and how, after a lab machine finishes humming. The OIG closed that recommendation the same day the report came out. Which raises a blunt question. If the paperwork looks fixed in a single afternoon, how long have the patients been living with the gap?

    What VHA Directive 1088(1) Actually Demands

    VHA Directive 1088(1), issued July 11, 2023, is not exactly beach reading. It sets requirements for timely, traceable communication of test results to both providers and patients. The directive spells out responsibilities, time frames, and documentation so there is a clear trail from the lab to the chart to the patient. The whole point is to stop test results from vanishing into the electronic equivalent of a desk drawer.

    When the OIG tells Mountain Home to develop written, service level workflows, it is saying that each clinic and service line needs a step by step process that matches the directive. Who reviews the result. How quickly. How abnormal findings reach the treating clinician. How and when the patient gets notified. How the contact gets documented so supervisors and inspectors can verify that someone actually did the job.

    That may sound bureaucratic. It is also the difference between a caught tumor and a missed one. Directive 1088(1) exists because the system has a long history of test results that fell through cracks wide enough to swallow an entire oncology ward.

    Staffing Shortages Meet Paper Thin Workflows

    The inspection of Mountain Home does not land in a vacuum. In the VA OIG’s fiscal year 2023 staffing shortages report, the same system shows up in Table C.58 with shortages across a familiar roster of jobs. Social workers. Nurse anesthetists. Practical nurses. Nursing assistants. Custodial workers. Food service workers. In other words, the people who stabilize a patient, keep the operating room moving, and make sure the place does not literally fall apart.

    Short staffing does not just mean longer waits in the lobby. It means that nurses race between beds, clerks juggle phones and inboxes, and supervisors quietly accept that some tasks will not get done. When there is no clear, written workflow for test result communication, the missing tasks often involve calls that no one can see. A lab result comes back. The ordering provider is off, or already drowning in alerts. A nurse means to follow up after the next medication round. A reminder gets buried. No policy pins responsibility on a specific role, within a specific time frame, with a specific way to document closure. The patient never hears a word.

    The scheduling breakdown at Mountain Home is not isolated. As covered in our report on the VA community mental health system, 128 out of 133 VA healthcare systems failed to meet the department’s own seven-day standard for scheduling mental health consults in FY2025 — a pattern that begins with the same undocumented, untracked workflow gaps visible at Mountain Home.

    That is the context in which the Mountain Home inspection tells leaders to put workflows on paper. Not because veterans need more binders. Because in an understaffed system, anything that is not written, tracked, and measured will be the first thing to disappear.

    Mountain Home Is Not An Outlier

    The OIG did not invent concern about test result communication for Mountain Home. It has been walking this same trail across the country. At the VA Dublin Healthcare System in Georgia, an April 2024 root cause analysis documented 25 patient safety events tied to failures in communicating test results. The OIG’s March 2025 report on Dublin tied those events directly to gaps in how results moved from lab to provider to patient.

    In February 2025, the OIG reported on the VA Salem Healthcare System in Virginia and found problems with communication of urgent and noncritical test results, again citing VHA Directive 1088(1). In December 2024, the OIG’s review of VA Durham in North Carolina concluded that leaders lacked hospital wide oversight to validate whether providers followed requirements for communicating test results. That is the same directive number haunting multiple campuses from Georgia to North Carolina to Virginia to Tennessee.

    Meanwhile, Mountain Home has drawn attention for issues well beyond lab results. In 2024, the House Committee on Veterans Affairs announced an investigation into allegations of workplace misconduct at the Quillen VA Medical Center. The same campus that now needs to formalize how it tells patients their test results was already on the congressional radar for broader cultural and management concerns.

    Layer on top of that a broader federal critique. A Government Accountability Office report, GAO 26 107528, examines how VA reviews and reports providers with clinical care concerns and calls for better training and oversight. Different investigators. Different document numbers. Same theme. The system struggles to consistently identify, track, and respond when patient care depends on staff following through.

    What A Missed Test Result Really Means

    The phrase “test result communication failure” sounds like something you fix with a software patch. The reality is uglier. A missed pathology report can mean a cancer that moves from treatable to terminal. A lab value that never reaches a clinician can mean sepsis that runs unchecked. An imaging finding that sits unreviewed can turn a manageable condition into a permanent disability.

    Every inspection and directive cited above exists because somewhere, a veteran sat at home waiting for a call that never came. Families do not sue over high level policy memos. They sue, and grieve, over the scan that no one followed up.

    This is why the timing in the Mountain Home report deserves scrutiny. The OIG issued the recommendation on August 28, 2026 and closed it the same day. On paper, that means the facility responded quickly and accepted the requirement to create those written workflows. In practice, the same day closure tells the public very little about whether the new procedures exist on the ground, whether staff know them, or whether anyone will check compliance three months from now.

    When a watchdog closes a recommendation the day it appears, it signals trust in leadership promises and in the documentation provided. It does not tell us how many veterans experienced delayed or missed results before the paperwork caught up. It does not tell us whether the same staffing shortages that drove the problem will sabotage the solution.

    So the question practically asks itself. In a system that needed a 2023 directive to spell out how to communicate test results, a string of OIG reports from Dublin to Durham to Mountain Home, a congressional investigation, and a GAO warning about weak oversight of problematic providers, how confident should a veteran feel that a normal lab result and a life changing one will both trigger the right call, at the right time, from the right person?

    Mountain Home has stood for veterans since 1903. Its history is carved in stone on a National Historic Landmark campus. The real test now is written somewhere else. In the workflows, checklists, and audit trails that show whether a twenty first century veteran will hear about a dangerous test result before it is too late.

    The deeper context for these failures is documented in our coverage of the $1.7 billion blind spot in VHA eligibility determinations — a systemic audit of how the VA’s internal guidance, broken scheduling software, and phantom wait times combine to fail veterans at every step of the care access chain.


    Fediverse Reactions