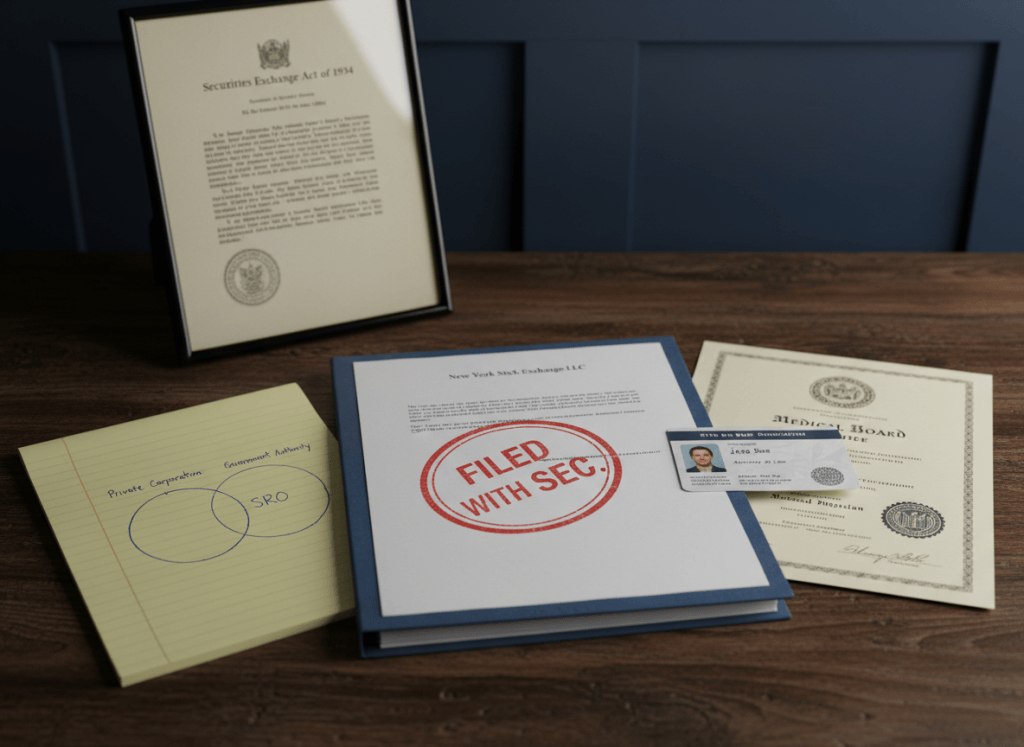
The New York Stock Exchange, as any diligent reader of an SEC filing will notice buried in the letterhead, is an LLC. Not a bureau, not a commission, not a branch of anything resembling the federal government. It is a subsidiary of Intercontinental Exchange, a publicly traded company with shareholders who would very much like a return on their investment.
And yet the NYSE writes rules, in this case NYSE Rule 1210, that determine how long a stockbroker who fails a licensing exam must sit in the penalty box before trying again. It publishes those rules through the Federal Register. It submits them to a Commission with the word “Securities” in its name. It behaves, in every visible respect, like a government agency, because Congress decided in 1934 that it should be allowed to.
This is the self-regulatory organization, or SRO, and it is one of the more elegant tricks in the American regulatory playbook.
Rather than build a federal bureaucracy large enough to police every trading floor and brokerage in the country, Congress simply deputized the industry to police itself, with the government reserving a veto and a badge. The result is a hybrid creature that cashes private paychecks while wielding public authority, and that hybrid nature is exactly why nobody quite knows what to call it when asked.
A Regulatory Agency That Turns a Profit
The legal architecture is straightforward enough on paper. Section 6 of the Securities Exchange Act of 1934 requires securities exchanges to register with the SEC and to adopt rules governing their own members, rules that must, among other things, prevent fraud and manipulation and promote “just and equitable principles of trade.”
The SEC’s own historical account of this arrangement traces the impulse back to a practical concession, one first voiced by an Assistant Secretary of Commerce in 1963, that direct government regulation of markets “on a wide scale” was simply too unwieldy to attempt (SEC Historical Society). Better, the thinking went, to let the exchanges regulate themselves, with Washington holding a leash.
That leash is real. Under Section 19 of the Act, an SRO must submit every proposed rule change to the SEC, which is precisely the mechanism on display in Release No. 34-106460, the filing that prompted this piece; NYSE proposing to shave FINRA’s own qualification exam waiting periods down to match, filed under a provision that lets “immediately effective” changes take hold while the Commission merely watches from the wings (SEC Release No. 34-106460, File No. SR-NYSE-2026-44).
The SEC can suspend an SRO rule within 60 days if it senses trouble. It rarely bothers. FINRA, the successor to the old National Association of Securities Dealers and now the primary regulator of broker dealers nationwide, occupies the same strange perch, a nonprofit corporation that nonetheless carries the statutory power to fine, suspend, and expel the very firms that fund it through membership dues.
Cornell’s Legal Information Institute puts the arrangement in blunter terms than the SEC ever would, noting that Congress built in “more stringent oversight” precisely because lawmakers recognized the conflict of interest lurking inside the design, the fox, as the encyclopedia entry puts it, guarding the chicken coop (Cornell LII).
The fox has so far kept the coop reasonably tidy, though the 2008 financial crisis and a steady drizzle of enforcement settlements suggest the guarding is more aspirational than absolute.
The Robe Wears the Badge Too
Securities markets are the flashiest example, but they are far from the only industry that gets to write its own rulebook.
Ask a lawyer who regulates lawyers and the honest answer, in most states, is other lawyers, operating under a license from the state’s highest court. The Washington State Bar Association, to take one plainly worded example, “operates under the delegated authority of the Washington Supreme Court” to license and discipline the state’s attorneys, administering exams, maintaining records, and running the entire professional discipline system “without public funding” (Washington State Bar Association).
California’s arrangement is stranger still. The State Bar there was established by statute in 1927 as a public corporation, yet the state’s own Supreme Court has insisted, in litigation over just this question, that the legislature’s involvement “does not alter or affect its constitutional and inherent regulatory authority over the bar” (State Bar of California).
Nobody in Sacramento is quite sure whether the State Bar is a government agency, a private association, or some administrative changeling that shape shifts depending on which court is asking.
The justification offered for this arrangement, at least by the people who benefit from it, is that self-regulation preserves judicial independence from the other two branches, a genuinely serious argument dressed up, not incidentally, as a professional cartel’s best defense of its own gatekeeping power.
The American Bar Association’s Model Rules make the same case for lawyers that the SEC once made for stockbrokers, namely that the industry, not the state, should hold the whip, and that the whip will somehow be wielded more wisely for it.
Medicine, Accounting, and the Long Tail of Delegated Trust
The pattern repeats across American professional life with a consistency that ought to unsettle anyone who assumes a license means a government inspector signed off on it. State medical boards, composed overwhelmingly of physicians, license and discipline doctors under authority delegated by state legislatures.
Accounting has its own version in state boards dominated by CPAs. Even arbitration, that quiet corner of civil law where most consumer and employment disputes now go to die, runs through the American Arbitration Association, itself recognized as an SRO with statutory duties under securities law (Wikipedia, Self-regulatory organization).
In every case the pitch is identical, that professionals understand their own profession better than a generalist bureaucrat ever could, so let them write the rules, subject to a government stamp that arrives after the fact and rarely gets withheld.
What ties the securities exchange to the state bar to the medical board is not statutory language, which varies wildly, but a shared bet that the regulated industry, given the pen, will regulate itself more competently and more cheaply than the government could manage alone.
Sometimes that bet pays off in exactly the dull, bureaucratic fashion intended, a waiting period trimmed from 30 days to 15, filed, published, forgotten. Other times the fox remembers what it is.
The Ledger So Far
None of this is secret and none of it is new; the SEC’s own historians trace SRO structures back more than two centuries and treat the arrangement as a settled compromise rather than a scandal (SEC Historical Society).
But settled is not the same as scrutinized, and an institutional structure that quietly licenses lawyers, disciplines brokers, and adjudicates arbitration claims, all while carrying letterhead that says “LLC” or “Association” rather than “Department” or “Bureau,” deserves more attention from the public it nominally serves than a stray footnote in a Federal Register notice.
The government did not disappear when it delegated these powers. It simply changed its clothes.

