There is a particular flavor of institutional rot that does not announce itself with a stolen Ferrari or an embezzled yacht. It announces itself with paperwork so lazy it becomes its own confession. In a new Justice Department Inspector General audit of $105 million in federal victim assistance grants flowing through the Michigan Department of Health and Human Services, auditors found a subrecipient director whose activity reports were identical, pay period after pay period, for years. Not similar. Identical. The kind of identical that suggests a human being decided, once, what percentage of their time belonged to which grant, then stopped thinking about it entirely, apparently confident nobody downstream would ever check the math against reality.
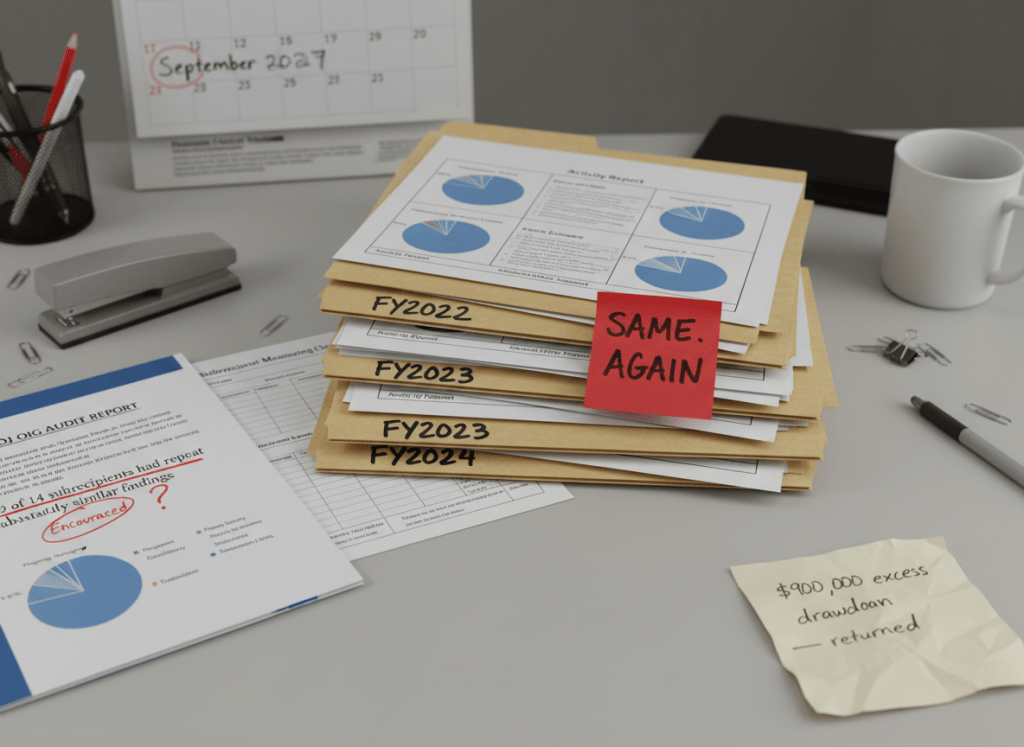
Somebody did check. Michigan DHHS itself flagged the pattern, first in a monitoring review dating back to fiscal year 2021. And flagged it again. And again, through fiscal year 2025, by which point the department’s own report on the matter had degraded into a bureaucratic shrug; a note that “future repayment may be requested” should the identical timesheets continue to appear identical. Four years is a long time to keep discovering the same fire and responding by writing a memo about how, next time, there might be consequences.
A Culture of Encouragement
This is not an isolated lapse dressed up as a pattern; it is the pattern. The Office of Justice Programs grants at issue, three Victims of Crime Act formula awards covering fiscal years 2022 through 2024, fund a genuinely vital state apparatus. Michigan’s Division of Victim Services channels the money to more than 200 community organizations providing crisis intervention, forensic exam reimbursement, shelter, and legal advocacy to survivors of domestic violence, sexual assault, and child abuse. Nobody is disputing that the underlying work matters. What the audit disputes is whether anyone in Lansing was prepared to make subrecipients actually fix what monitoring reviews kept turning up.
Auditors pulled a sample of 14 subrecipients’ monitoring histories across the five year review cycle and found that 9 of them had repeat or substantially similar findings. In one case, financial audits conducted in fiscal years 2022 and 2024 turned up eleven repeat findings at the same organization, including unsupported expenses and improperly calculated indirect costs; the same deficiencies persisted across the two year gap despite the subrecipient having been formally required to update its processes. The audit’s own language captures the department’s operating philosophy with more precision than any editorial gloss could manage; Michigan DHHS “identified concerns but did not explicitly require subrecipients to take corrective action, rather encouraged subrecipients to resolve the issues before their next monitoring review.” Encouraged. As though four year old fraud indicators were a matter of gentle persuasion rather than federal compliance.
Michigan DHHS officials offered auditors a reasonable sounding excuse; some review periods overlapped, leaving subrecipients insufficient time to correct issues before the next check arrived. It is a plausible administrative headache. It does not explain why, when a director’s timesheets never once varied across years of reviews, “encouragement” remained the department’s entire enforcement toolkit. Nor does it explain the parallel finding that of 22 subrecipient contract reviews auditors examined, 19 turned up errors in the performance data those subrecipients reported to the federal Performance Measurement Tool system; wrong categories, service logs that did not match the numbers claimed. Michigan DHHS caught these errors and, per the audit, did not require subrecipients to correct them or revise how they tracked the data going forward. The department has since told auditors it now asks for amended reports when it spots discrepancies, an improvement whose arrival four audit cycles late says something on its own.
The Cash That Sat Around Too Long
While the timesheet saga is the report’s most vivid moment, it shares billing with a second failure that deserves its own brief entry in the ledger of institutional forgetfulness. Federal rules require grant recipients to keep drawdown requests to the minimum needed for reimbursements due within ten days; essentially, do not sit on federal cash. Michigan DHHS transferred roughly $3.2 million in expenditures between two overlapping VOCA grants and, in the shuffle, ended up drawing down funds it had effectively already drawn once, leaving $900,000 in excess federal cash sitting in state coffers for over a month, discovered only because the auditors went looking.
The department returned the money, eventually, and explained that it had not known about the ten day repayment requirement, this despite a nearly identical episode having already surfaced in a prior review by the OJP’s own Chief Financial Officer’s office. A department managing over a hundred million dollars in federal victim services money discovering, for a second time, that it does not know how quickly federal cash must move is not an anecdote so much as a diagnostic.
Money That Michigan Says Belongs to Michigan
The audit also questioned $238,982 in administrative expenditures, the bulk of it $169,659 in pension and retirement contributions charged to the VOCA grant for employees whose eligibility for those specific benefits could not be verified. Michigan disagreed, at length, citing state law that spreads certain unfunded pension liabilities across the entire state payroll regardless of individual eligibility, and declined to concede the point even in its formal response to the draft report. The Office of Justice Programs sided with its own auditors; federal cost allocation rules require charges to match the actual pattern of benefits received by the employees whose salaries hit the grant, not a statewide average. It is, in miniature, a preview of the same institutional posture visible everywhere else in this report; acknowledge the smaller, cheaper findings gracefully, agree to return the money nobody will fight for, and hold the line only where holding it costs the most.
What Comes Next
Justice Department auditors issued eight recommendations. The Office of Justice Programs agreed to all of them without qualification. Michigan DHHS agreed with four, contested the pension cost finding across three separate recommendations, and simply declined to state a position on a fifth, even while agreeing to write the check. Every recommendation in this report is now formally “resolved” in the federal accountability sense of the word, meaning paperwork exists committing someone to eventually do something; Michigan has given itself until September 2027, more than a year from now, to finalize procedures ensuring subrecipients actually correct their deficiencies in a timely way.
That deadline sits uncomfortably close to another number in this report; the four years auditors spent watching one subrecipient’s timesheets stay exactly the same while nothing happened. Bureaucracy has a rhythm all its own, and in Lansing it appears to run on a five year monitoring cycle that resets itself before consequences ever quite arrive.

