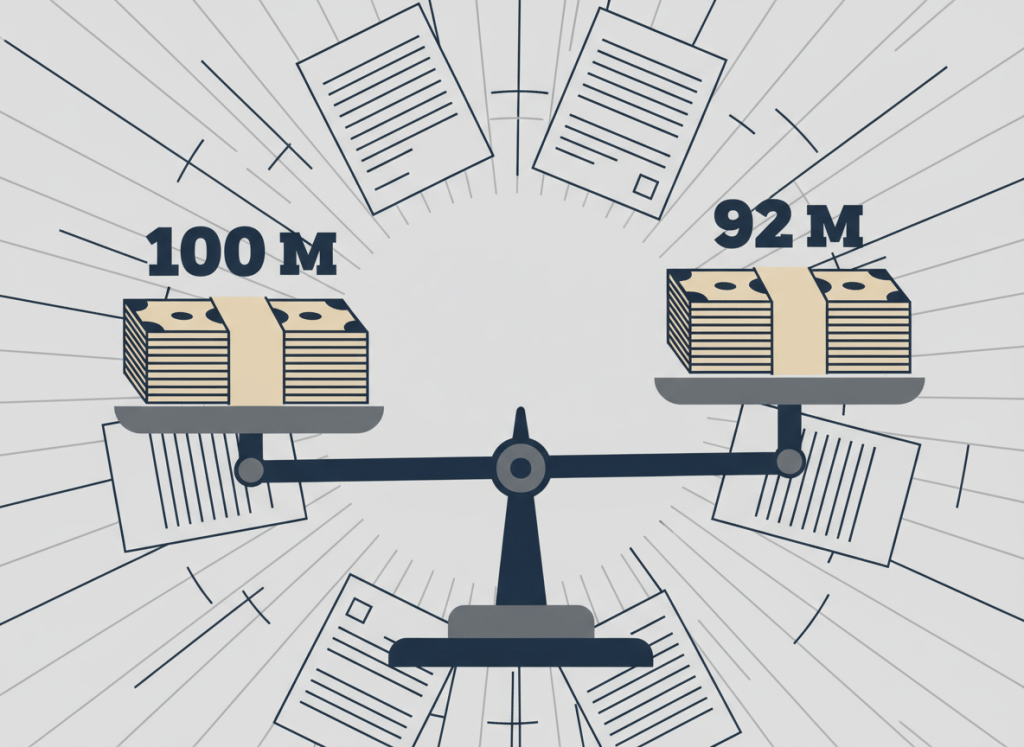
A company reports $100 million in revenue. Another reports $92 million. Both conducted essentially the same business, collected the same amount of money, and earned the same profit. The difference may come down to how they accounted for $8 million in customer incentives.
That is the kind of discrepancy the Financial Accounting Standards Board (FASB) is attempting to address through a proposed accounting standards update issued October 22, 2026.
The proposal concerns a deceptively simple question: When a business pays money to its customers, or to people doing business with those customers, should those payments be recorded as operating expenses or deducted from reported revenue?
Under existing generally accepted accounting principles, the answer depends on the nature of the payment and the relationship between the parties. But the rules have not explicitly addressed every arrangement, particularly those involving payments made outside a company’s direct distribution chain.
The result, according to FASB’s proposal, is inconsistent accounting treatment of economically similar transactions. For investors trying to determine how much business a company is actually generating, that distinction can matter considerably.
The Difference Between Revenue and Expense
Under Accounting Standards Codification Topic 606, Revenue from Contracts with Customers, payments made to customers generally reduce the transaction price and therefore reported revenue. An exception applies when the payment purchases a distinct good or service from the customer.
The distinction becomes more complicated when the payment goes somewhere other than the company’s immediate customer.
Consider a hypothetical online marketplace that earns fees from merchants selling products through its platform. To attract shoppers, the marketplace provides promotional credits to people making their first purchases.
The marketplace’s contractual customers are the merchants. The people receiving the promotional credits are shoppers, who may have no direct revenue-generating contract with the marketplace.
Should those credits be classified as marketing expenses, or should they reduce the revenue the marketplace reports from its merchant relationships?
Under the proposed clarification, the answer would depend partly on whether the marketplace explicitly or implicitly promised the incentives as part of satisfying its obligations to merchants, or whether the payments effectively represent price concessions.
An October 27 analysis by Deloitte identifies platform and intermediary businesses as among those most likely to be affected. It also describes promotional financing arrangements in which retailers make payments to third-party banks on behalf of customers.
In either case, the payment may be economically connected to a sale even though the money never passes directly to the company’s contractual customer. The accounting treatment determines where the payment appears in the financial statements.
Same Transaction, Different Revenue
Suppose a business earns $100 million in revenue and spends $8 million providing incentives connected to those sales.
If the incentives qualify as operating expenses, the company may report $100 million in revenue and recognize the $8 million separately. If the incentives must instead be treated as reductions of the transaction price, reported revenue would fall to $92 million.
Assuming all other accounting effects are identical, the company’s bottom-line profit could remain unchanged. Its reported revenue, however, would be 8 percent lower.
That difference can influence revenue-growth comparisons, gross-margin calculations, and valuation measures that rely on reported sales. It can also complicate comparisons between companies using similar business models but different accounting interpretations.
The example is hypothetical and does not establish that either treatment is appropriate for any particular transaction. The actual classification depends on the contractual arrangements and applicable accounting guidance.
Nevertheless, it illustrates why FASB is seeking greater consistency. As the Journal of Accountancy reported October 22, the proposed changes address situations in which existing guidance does not explicitly determine whether payments outside a direct distribution chain qualify as consideration payable to a customer.
FASB is not proposing that every promotional payment automatically reduce revenue. Instead, it would clarify the circumstances under which companies must evaluate such payments using the existing customer-consideration rules.
An Accounting Problem With a Longer History
The issue did not emerge overnight. According to Deloitte’s analysis, FASB’s Emerging Issues Task Force recommended addressing the matter in June 2026, following concerns about inconsistent financial reporting. The Board added the project to its technical agenda in August.
The proposal would clarify that payments made on behalf of customers, or to customers of those customers, fall within the relevant accounting guidance when connected to satisfying a contractual promise.
That connection may arise through an explicit commitment, an implicit promise established by customary business practices, or a price concession that the customer reasonably expects.
The proposed clarification is significant because it addresses the substance of a transaction rather than simply the identity of the person receiving the payment. A company could not necessarily avoid consideration-payable-to-a-customer analysis merely by routing an incentive through a third party.
At the same time, the proposal preserves the existing exception for payments made in exchange for distinct goods or services.
FASB is also seeking feedback on an unresolved consequence of the proposed approach: negative revenue.
Such a result can arise when payments classified as reductions of revenue exceed the revenue recognized from the associated customer arrangement. The Board has not proposed a new rule resolving how all such amounts should be presented, but it has asked stakeholders whether additional standard-setting is necessary.
That leaves an important question for investors and accountants alike. Clarifying which payments reduce revenue may improve consistency, but it could also expose presentation questions that existing standards do not fully resolve.
The SEC’s Role: Making the Numbers Readable
The accounting proposal is accompanied by a less visible but important change to the machinery of federal financial reporting.
On October 29, the Securities and Exchange Commission announced a proposed update to the U.S. GAAP Financial Reporting Taxonomy, the standardized system used to classify financial information in electronic filings.
The taxonomy supports eXtensible Business Reporting Language, or XBRL, which allows computers to identify and compare financial data across companies. Rather than treating a financial statement as an ordinary document, XBRL attaches standardized electronic labels to individual financial facts.
The proposed taxonomy changes include modifications to accounting references, new elements identifying accounting standards updates, and the retirement of elements associated with guidance that is no longer applicable.
FASB’s eight-page taxonomy release notes, identified as File Reference No. 2026-ED700, describe the technical proposal.
The distinction between the accounting standard and its electronic reporting taxonomy is important. FASB establishes financial-accounting standards. The SEC oversees securities reporting and determines which taxonomy versions may be used in filings submitted through its Electronic Data Gathering, Analysis and Retrieval system, better known as EDGAR.
The SEC expressly cautioned that publication of the proposed taxonomy changes does not constitute Commission approval of corresponding regulatory changes.
As XBRL US explained in its October 28 announcement, the taxonomy proposal is intended to accommodate the underlying accounting clarification.
The proposed electronic changes do not themselves establish that investors will receive additional disclosures identifying every customer incentive. Whether the resulting reporting will provide greater transparency into these arrangements remains an open question.
What Happens to Previously Reported Revenue?
Another important issue is how companies would implement the revised guidance.
FASB has proposed allowing companies to choose between modified prospective and modified retrospective transition approaches.
Under the prospective approach, companies generally would apply the revised guidance to payments made or promised after adoption without restating earlier financial results. The retrospective alternative would require adjustments to the comparative financial periods covered by the transition method.
Those choices could affect how easily investors compare financial results before and after adoption.
A company applying the guidance prospectively might report revenue under different classification practices across successive periods, while another company using the retrospective approach could adjust comparative figures.
Neither outcome necessarily indicates an accounting error. But both create potential complications for financial analysis.
The Board has not yet established an effective date. According to an October 29 technical summary by EY, early adoption would be permitted under the proposal.
The eventual effect will depend on the final standard, companies’ existing accounting practices, and the payment arrangements involved. No industrywide estimate of potential revenue reclassification has been established in the materials reviewed for this article.
A Question of Comparability
The broader issue is not whether companies should be permitted to offer rebates, promotional credits, financing incentives, or other payments to encourage business. Such arrangements are commonplace, and their existence does not imply misconduct.
The issue is whether financial statements consistently communicate the economic substance of those arrangements.
When one company reports a customer-related payment as an expense and another deducts an economically similar payment from revenue, investors may be comparing figures that reflect different accounting judgments rather than different commercial performance.
FASB’s proposal acknowledges that problem and attempts to narrow the room for inconsistent interpretation.
It does not establish that companies have intentionally inflated revenue, nor does it demonstrate that any particular issuer has violated existing accounting standards. Those conclusions would require evidence from company-specific disclosures, contracts, accounting policies, and potentially regulatory findings.
What the proposal does establish is that the existing framework has left enough uncertainty to warrant clarification. That is a meaningful admission in a financial-reporting system built around comparability.
Public Comments Remain Open
FASB is accepting public comments on the proposed accounting update through November 23, 2026. The associated taxonomy proposal carries the same deadline.
Comments on the taxonomy improvements may be submitted to xbrled@fasb.org, referencing File No. 2026-ED700.
The Board will consider stakeholder feedback before determining the final requirements and effective date.
For investors, the question is whether the revised guidance will make reported revenue more comparable across companies operating under similar economic arrangements.
For regulators, the challenge is ensuring that financial-reporting rules and the electronic systems used to communicate them accurately reflect the transactions being reported.
And for companies, the question may ultimately be whether money spent attracting customers belongs below the revenue line or should never have been included in reported revenue in the first place.
The cash may be the same. The numbers investors see may not be.

